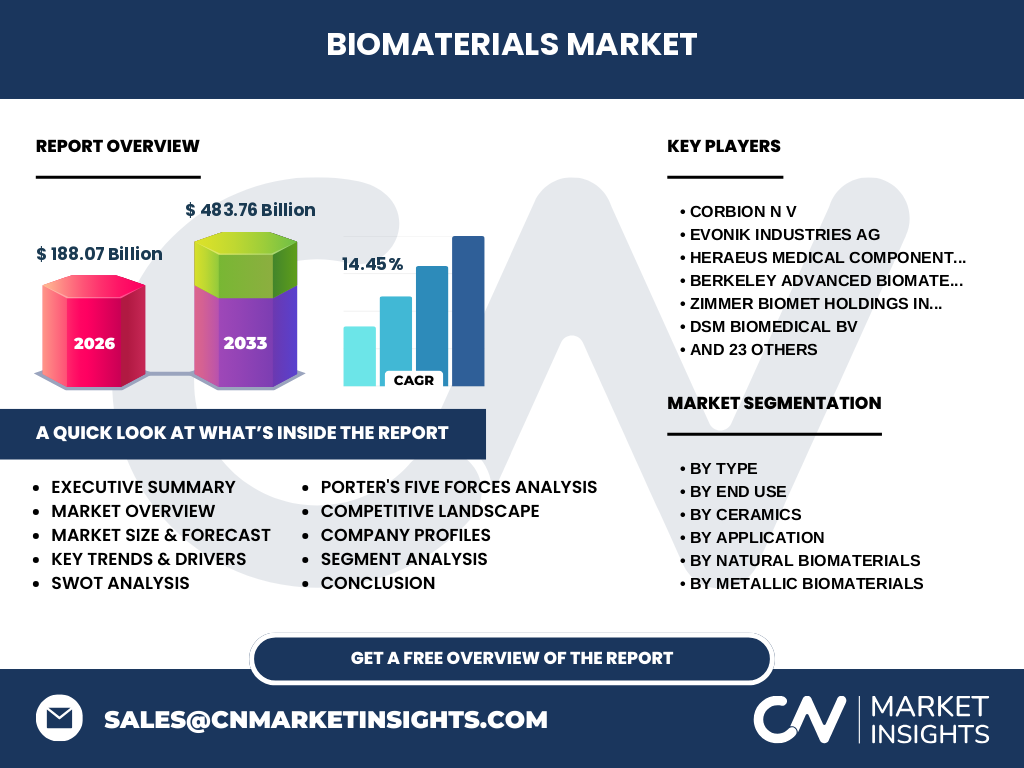
Market overview of the Biomaterials Market
The Biomaterials Market encompasses natural and synthetic substances engineered to interact with biological systems for medical purposes. Valued at 188.07 Billion in 2026, the industry underpins modern surgical implants, regenerative medicine, and targeted drug delivery systems across global healthcare networks.
What are the primary drivers and restraints shaping the Biomaterials Market?
Structural growth drivers include aging demographics and rising orthopedic trauma cases, while regulatory bottlenecks from agencies like the FDA present notable constraints. Supply chain volatility for medical-grade titanium and specialized polymers further challenges manufacturing throughput.
Emerging trends and growth patterns in the Biomaterials Market
The industry is shifting rapidly toward patient-specific 3D-printed implants and bioresorbable polymers. Companies like PolyNovo Limited and Invibio Ltd. are pioneering customizable scaffolds that accelerate osseointegration and reduce long-term revision surgeries.
COVID-19 impact analysis and recovery trajectory for the Biomaterials Market
Elective surgery cancellations during the pandemic suppressed demand for non-urgent cardiovascular and orthopedic devices. However, robust fiscal stimulus and elective procedure backlogs have driven a strong post-pandemic volume recovery.
Competitive landscape and strategic dynamics in the Biomaterials Market
Market concentration remains moderate to high, with enterprise leaders like Zimmer Biomet Holdings Inc., Stryker Corporation, and Evonik Industries AG dominating through aggressive M&A and proprietary coating technologies that enhance implant longevity.
Executive summary of the Biomaterials Market
Driven by a projected CAGR of 14.45% from 2027 to 2033, the Biomaterials Market will expand from 188.07 Billion to reach 483.76 Billion by the end of the forecast period, anchored by surging innovations in tissue engineering.
Market forecast trajectory from 2027 to 2033
Our analysis indicates accelerated expansion as the market surges from its 2026 baseline to hit 483.76 Billion by 2033. This trajectory is powered by continuous reimbursement approvals for advanced bioceramics and degradable metallic alloys.
Segmentation analysis across product types and applications
The market is categorized by Metallic Biomaterial, Polymeric Biomaterials, Natural Biomaterials, and Ceramics. End uses span Hospitals and Clinics and Ambulatory Surgical Centers, serving applications from orthopedic reconstruction to complex cardiovascular interventions.
Regional market analysis and geographic performance
North America retains dominant revenue share due to advanced healthcare infrastructure and early adoption of regenerative technologies. Meanwhile, Asia-Pacific exhibits the fastest regional growth rate, propelled by expanding medical tourism in Southeast Asia.
In-depth regional review of key healthcare markets
European markets face stringent MDR compliance hurdles that favor well-capitalized firms such as CeramTec GmbH and KLS Martin Group. Concurrently, US markets prioritize high-throughput ambulatory surgical centers utilizing advanced wound healing matrices.
Company profiles and strategic positioning
Industry stalwarts like Corbion N V, Surmodics Inc., and Heraeus Medical Components LLC leverage vertical integration. They focus on proprietary polymer synthesis and precision metal fabrication to secure sticky supplier contracts with major OEMs.
Porter's Five Forces analysis of competitive intensity
Supplier power is moderate due to strict purity standards for raw metallic alloys. Conversely, buyer power is high among large hospital group purchasing organizations, while threat of substitution remains low given rigorous clinical validation hurdles.
SWOT analysis of the global biomaterials sector
Strengths lie in robust biocompatibility profiles of titanium and hydroxyapatite. Weaknesses involve high R&D attrition rates. Opportunities abound in neural tissue engineering, while threats center on macroeconomic inflation affecting raw material sourcing.
Value chain analysis from raw materials to end-users
The value chain originates with chemical and metallurgical refiners supplying medical-grade stock to component fabricators like Secant Group LLC and Gelita AG. These components are then assembled by device manufacturers before reaching clinical end-users.
Investment insights and high-potential areas
Venture capital and strategic acquirers are targeting bio-derived polymers and magnesium-based resorbable alloys. Investors should prioritize firms with validated clinical trial pipelines in ophthalmology and central nervous system regeneration.
Conclusion and key takeaways for industry stakeholders
The Biomaterials Market represents a high-conviction sector characterized by double-digit growth. Success requires navigating stringent regulatory frameworks while capitalizing on patient-specific regenerative medicine innovations.
Research methodology for baseline estimates
Our findings are triangulated by cross-referencing primary stakeholder interviews with C-suite executives, secondary trade registry data from medical device associations, and macroeconomic healthcare expenditure models across key global economies.
Scope of the report and coverage parameters
This report evaluates global market dynamics for biomaterials from 2026 through 2033. Geographic scope covers North America, Europe, Asia-Pacific, and Rest of World, focusing strictly on medical-grade materials utilized in human healthcare.
Recent developments, partnerships, and strategic moves
Recent strategic activity highlights aggressive R&D joint ventures among market participants like Cerapedics Inc. and Cam Bioceramics BV. Companies are actively expanding manufacturing footprints to secure localized supply chains ahead of anticipated regulatory updates.